
High Inflation is coming
Clearly we have reach a point where everyone feels inflation is impacting their day to day life. For the past 20 years people enjoyed relatively low inflation and prices are generally stable. Going forward I think we may face a different type of inflation more similar to other periods in past history.
Where did inflation came from no longer matters but how expectation of it will increasingly strengthen its power and resolve.
Think about it, do you expect prices to increase more next year than last year? If you are property buyer do you expect property prices to come down while building cost keeps rising? If you are a business owner will you project your cost to be up or down next year and the years that follows? These expectations if left unchecked will sooner or later turn inflation into a Godzilla typed monster that will destroy economies.
So with inflation central banks hands are tied and they no longer can use monetary stimulus to support the economy. In fact the generally accepted solution to tame inflation is to raise interest rates. The impact of rising interest rates will thus have a very key impact on all financial assets.
The long government bond rate which is also known as the risk free rate is a key dictator in the pricing of financial assets. Investors demands a certain amount of trade off for taking additional risk. It is a no brainer for an investor if the risk free rate is 10% versus choosing to invest in a business that returns 10%.
Now even if you are in your 50s, you probably haven seen risk free rates anywhere near 10%. So you really have to ask yourself what is the probability of it happening. The CPF ordinary account pays 6.5% interest from 1974 – 1985.
The CPF special account a rate setting mechanism peg to the 10 year Singapore Government Bond is now at 3.7%. This is very much within touching distance of the 4% floor for the special account. The likelihood of surpassing 4% is now very real. Now let’s assume the special account pays 5% interest, an investor should no longer be happy with investing in a REIT that give a 5% yield. Maybe an 7% yield may be more appropriate.
All else been the same, REITs will need to go down in price such that it gives a 7% yield with the same payout. This can happen very quickly as interest rate can change at an instant. This can also be said of companies that investor expect higher returns such as to compensate for the higher risk free rate.
We are currently seeing the scenario playing out in the US market as expectations of further rate hike fuels Price Earnings multiple compression. This is all happening during a time where many companies earnings remain very strong. Businesses that have any slight slow down droped like a rock like Netflix, Paypal, Walmart and many more.
Currently I see the economies at a crossroad. One scenario whereby inflation can be contain fairly quickly with aggressive rate hike to normalised interest rates of 3% -5%. This would mean more pain this year but things shall stabilise going into 2023
The other scenario points to inflation runs further ahead and rates increases plays catch up. In this case interest rate could soar to 10% and we get a market crash that is somewhat like the 99 Dotcom bubble crash. Investors should thus be prepared for both cases. Historically the assets that have done well during times of inflation includes, commodities, real estate and gold. Companies with real moats and pricing power will weather the storm better.
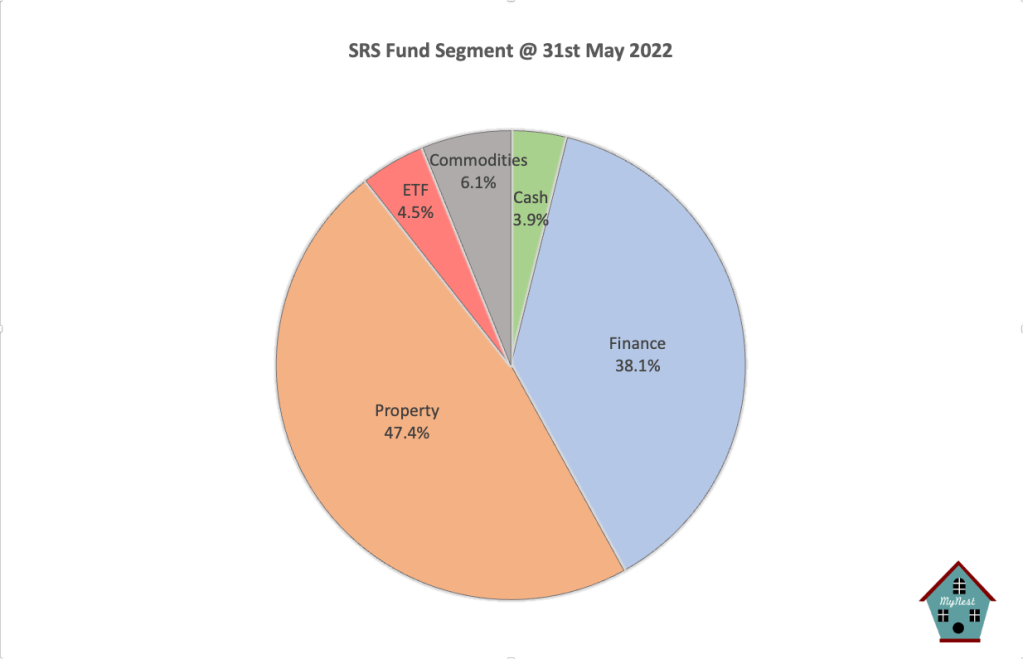
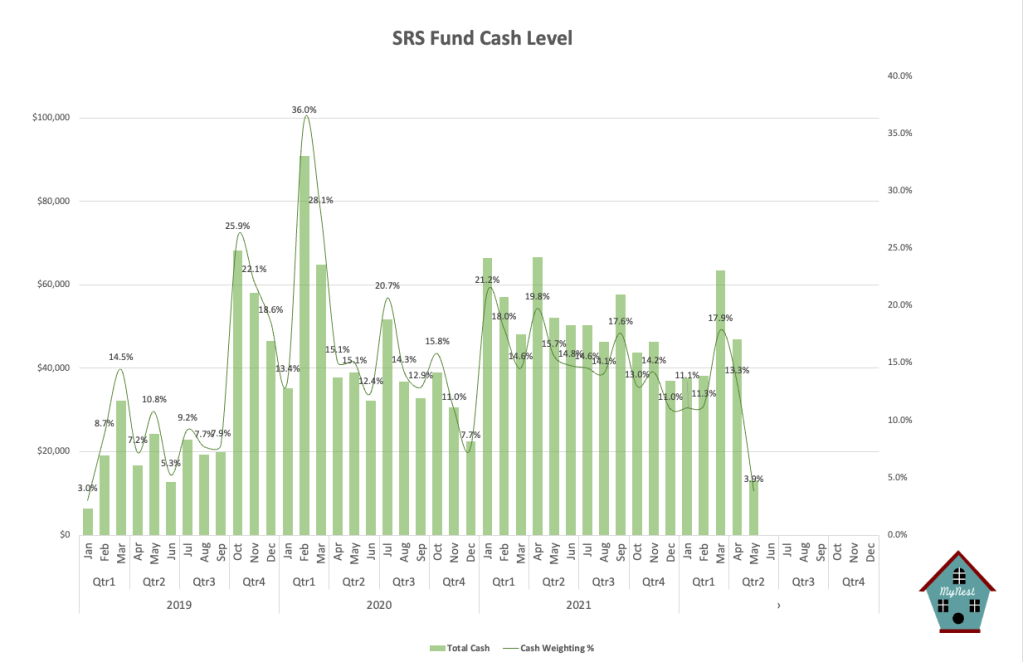
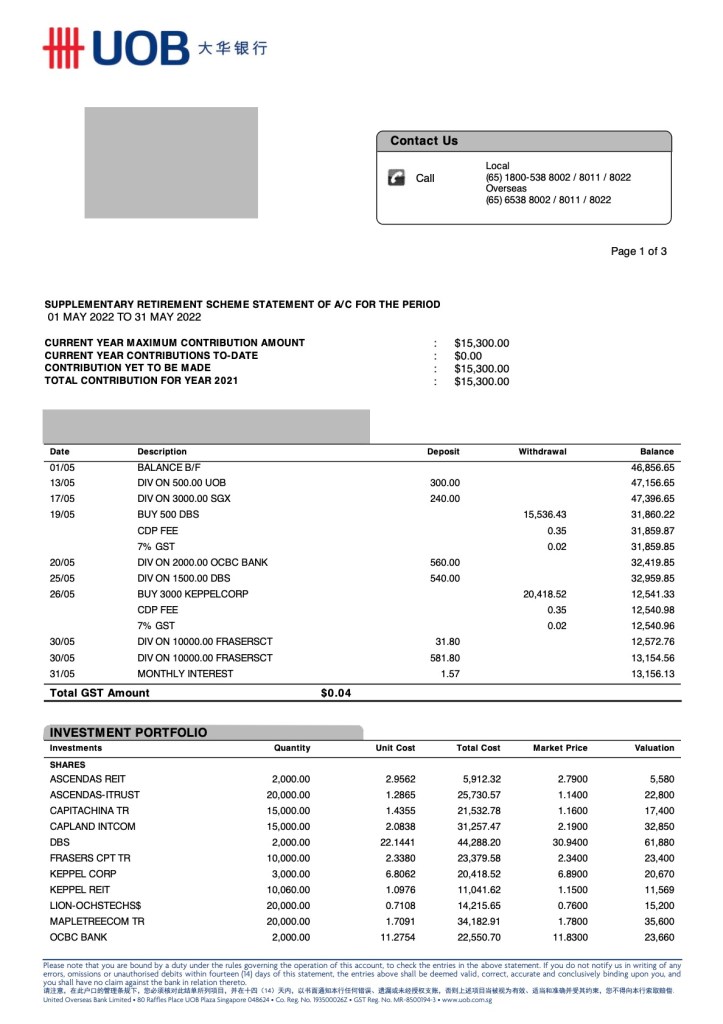
As such to position the SRS Fund for in a high inflationary environment I have begin to invest the excess cash in the fund into commodity typed play. In the month of May I have put up 6% of the fund to initiate a position in Keppel Corp which consist of an oil and gas component and a real estate component.
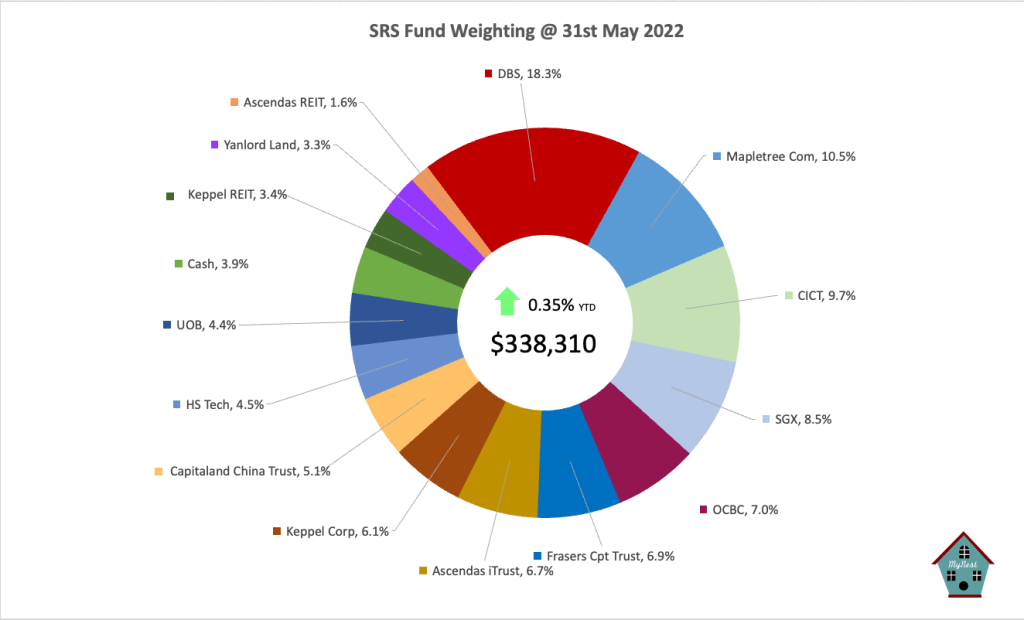
The SRS Fund remains slightly in the green year to date despite the fall in the general market in the month of May. This is mainly thanks to the dividend collected to cushion the fall in price of the many companies in the portfolio.
I am still fairly positive for the SRS fund to do well come end of the year as Singapore’s reopening and the gradual relaxation of the Chinese economy should provide some support against the strong inflationary headwind.



LATEST POSTS
-
MyNest US Fund Jan 25
2025 started with a furry of news and activities that may have further implacations on companies in the portfolio. The 2 key events I kept my eyes on was the following.
-

Jumbo Group Annual Report Review
Jumbo group was a position initiated into the SRS Fund due to my revenge travel boom thesis in Jun 2023. Back then I concluded that Jumbo is well positioned to take advantage of Singapore’s reopening to tourism. 18 months later, business was indeed brisk
-

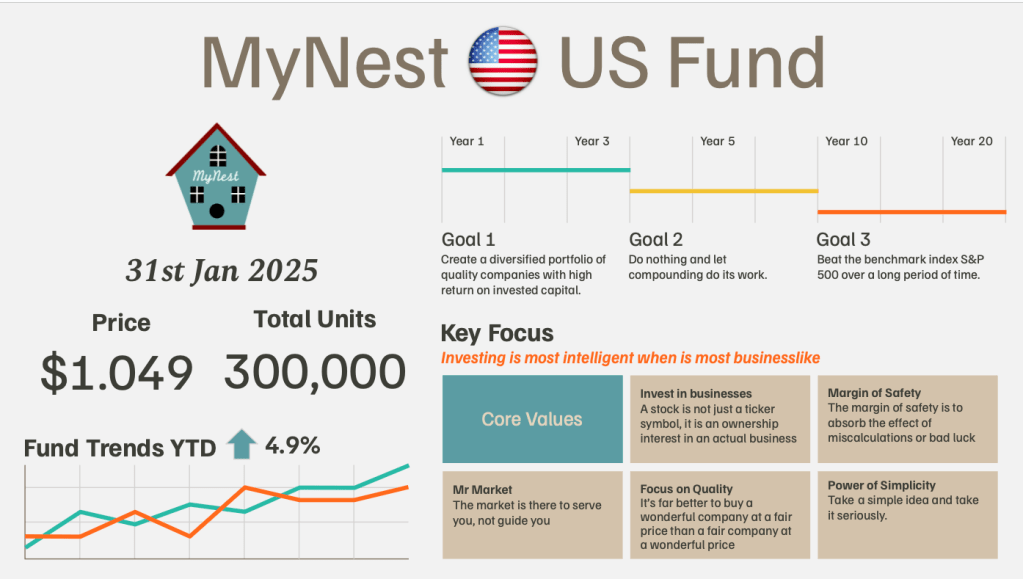
MyNest US Fund Launch
I started investing in the US Stock Market in 2021. Over a 4 year period, I have accumulated good investing experience and achieved some success in the US market.
-

The SRS Fund Dec 2024 Update
The SRS Fund had its best return in a year since its inception in 2024. SRS Fund value was up 19.4%, excluding new contributions. However, the SRS Fund underperformed its benchmark STI index which drums up a whopping 22% (Dividend included).
-
The SRS Fund Nov 2024 Update
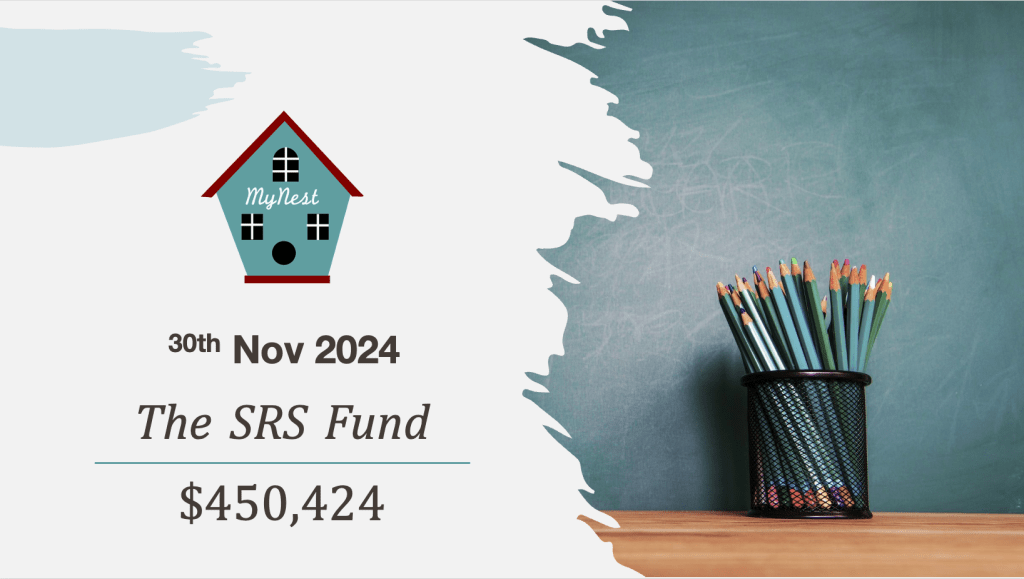
The US Presidential Election took centre stage for the month of November. Global stocks then rallied on the back of Donald Trump’s return to the white house. The euphoria took place across all asset classes, led by crypto, as bitcoin rallied past the 100k mark.
-
The SRS Fund Oct 2024 Update
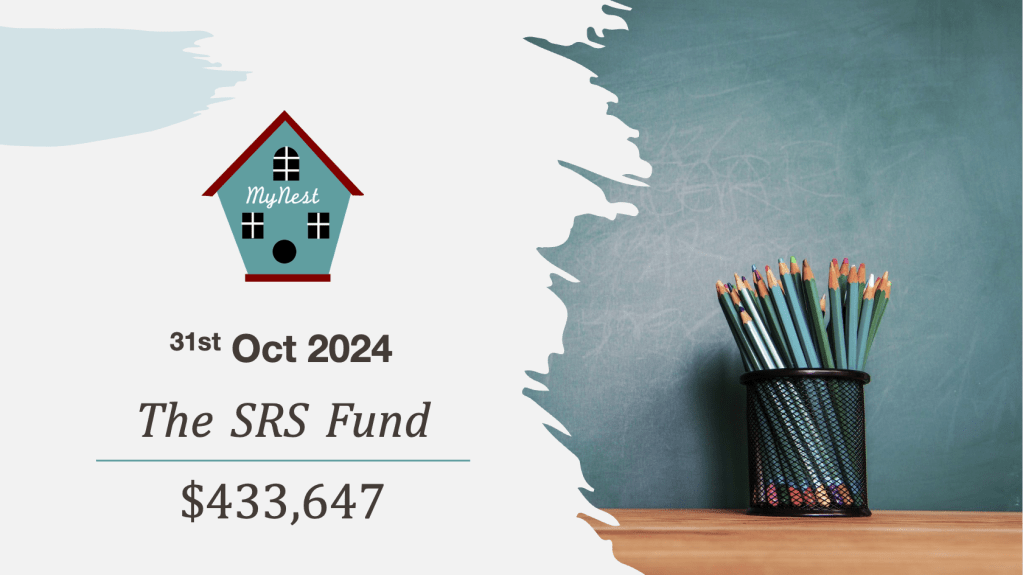
As the enthusiasm for the Fed interest rate cut and announced China stimulus subsided during October, the focus has now turned to upcoming earnings seasons.

