
What a difference a month make. This March we watch the banking crisis unfolded as something finally broke after long periods of interest rate increases. Both the casualties Silicon Valley Bank SVB and Credit Suisse are not technically close but their shareholders had been truly wiped out without a doubt. With this turn of event something interesting is transpiring in the bond market.
Since the turn of the year, the bond market begin to bet that the Fed will start to pause and turn around sooner rather than later as we watch interest rates across the curve starts to inch lower. When the bank crisis broke out mid March interest rates really begin its dive as investors shifted their assets into safety of bonds.
With the crisis unfolding, the Fed over that weekend guaranteed all deposits of SVB stemming out an immediate crisis but left open a possible slower contagion of fear by not guaranteeing all deposits throughout. At the FOMC, Jerome Powell reiterated the need for cautious as he keeps his eyes firmly on inflation with a quarter point hike. However, he also suggest they are close to the terminal rate and likely one more hike is in place before a long pause.
I believe the Fed will do what they say (even though they may be wrong) and market will have to adjust accordingly. As such interest rates will likely stay high for the rest of the year and more things will continue to break along the way. I am inclination at this point to look towards the commercial real estate market which have high leverage and are not restructured to withstand an extended period of high rates.
My view to inflation is that it is not a beast that can be easily tamed. A stab to inflation will see it retreat but investors thinking it will not fight back may be in for a nasty surprise. Inflation will likely stay volatile over the next decade and investors with a good sense of it will likely come up on top in such an environment.
The SRS Fund Review
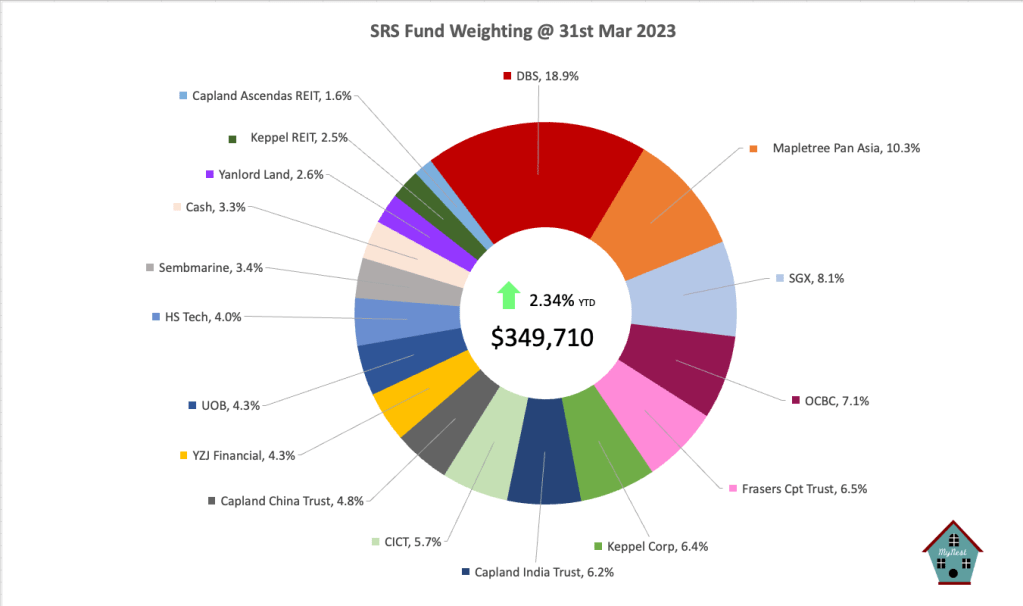
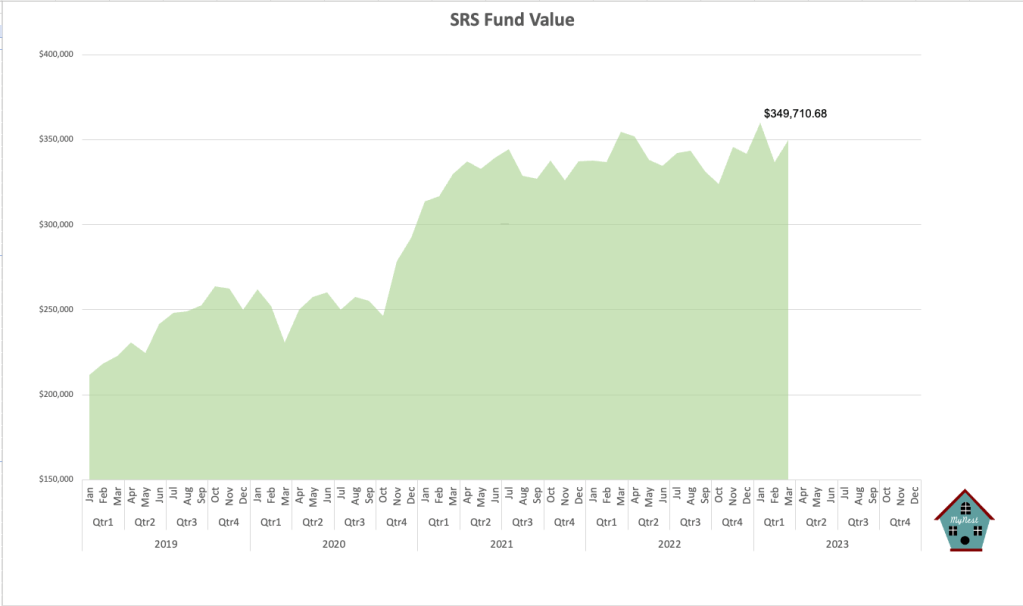
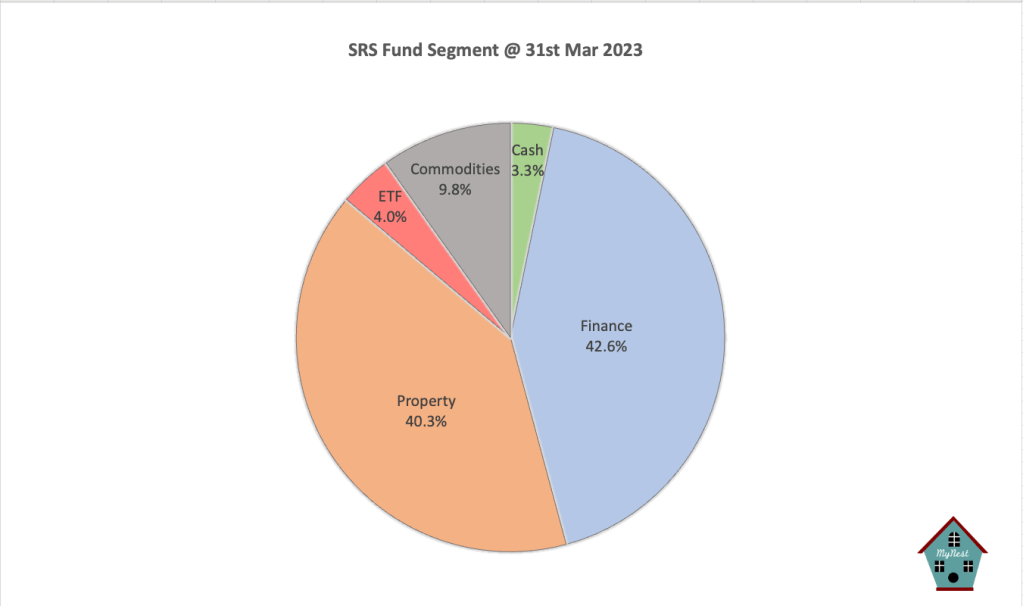
The SRS Fund recovered from Feb and is now back into the green up 2.34% year to date. I took the opportunity of the selloff in Sembmarine to buy more shares taking it up to 3.4% of the portfolio. The month saw rises across the board in particularly in REITs and Banks. After a lagging 2022, the fund is finally ahead of its benchmark the STI by a full 2%.
With REITs rebounding somewhat I may take the opportunity to trim some of the fund REITs holding to position the portfolio for greater interest rate volatility ahead. Banks are expected to do well for the year and I may put more cash to this sector when opportunity arises.
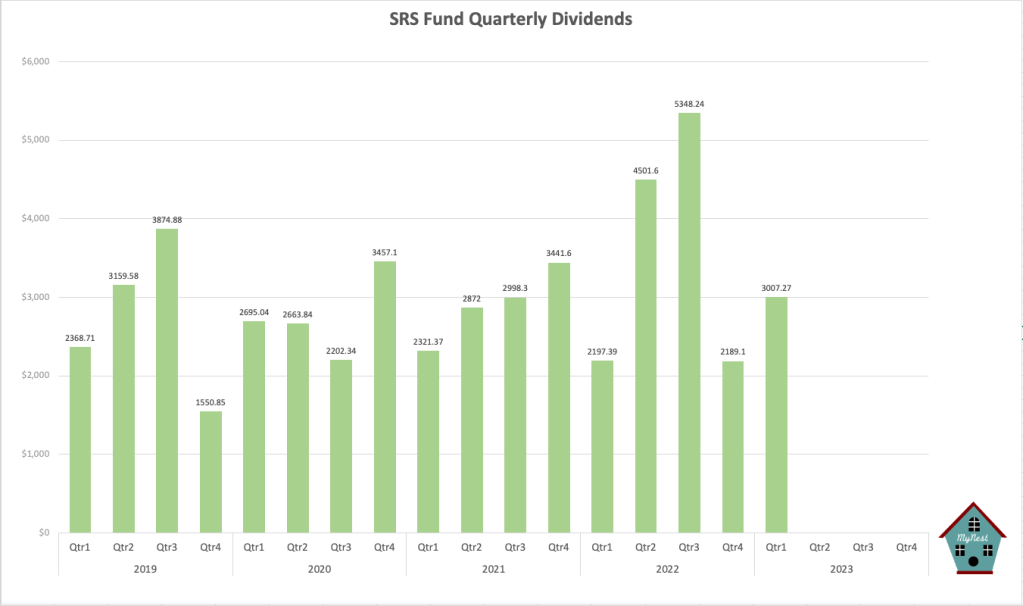
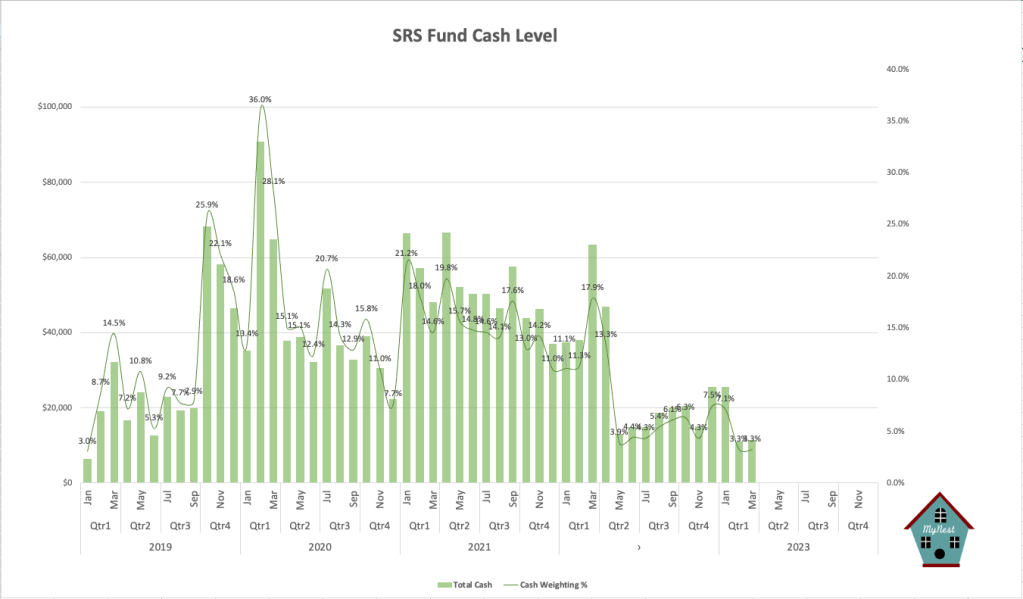
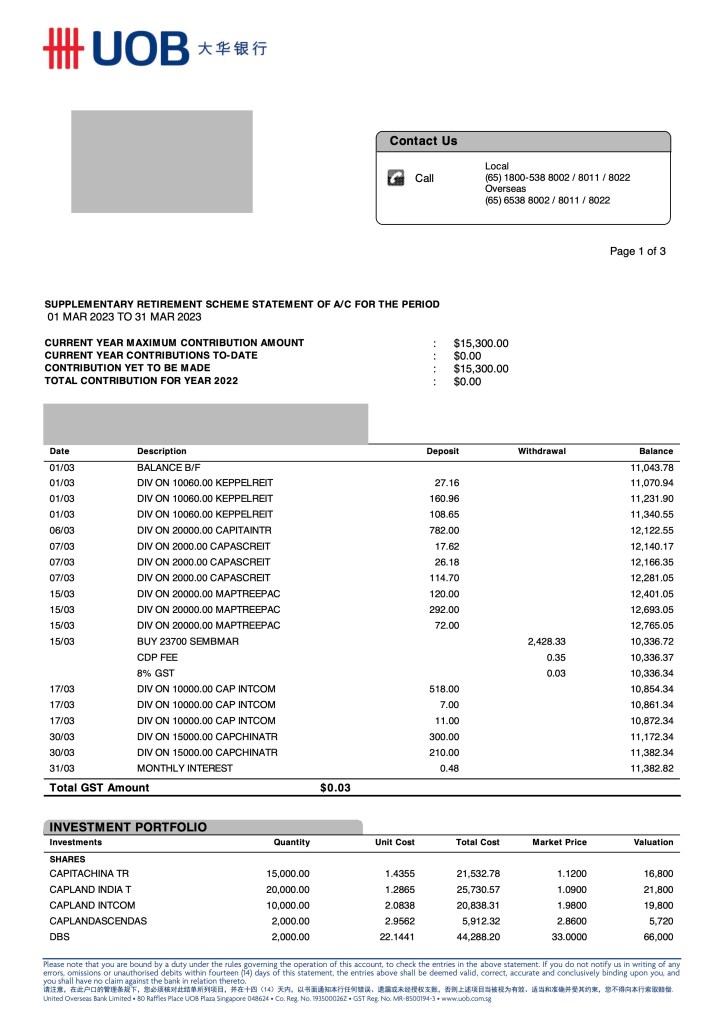
The SRS Fund see another record dividend inflow for Q1 with $3007.27. With a host of AGMs and quarterly earnings upcoming the dividend inflow is likely to continue in Q2. I am inclined to build up the SRS Fund cash position such as to prepare for any unforeseen volatility ahead.

-
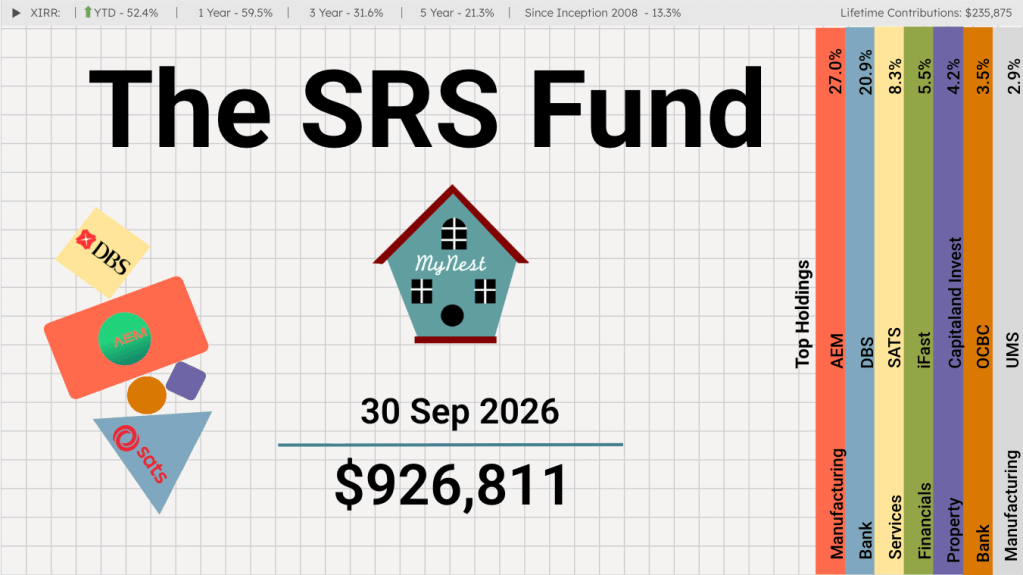
The SRS Fund Sep 2026
Sep brought a modest recovery in the SRS Fund, but it also left me thinking more carefully about how much of Singapore’s current economic and market strength is connected to the AI investment cycle.
-
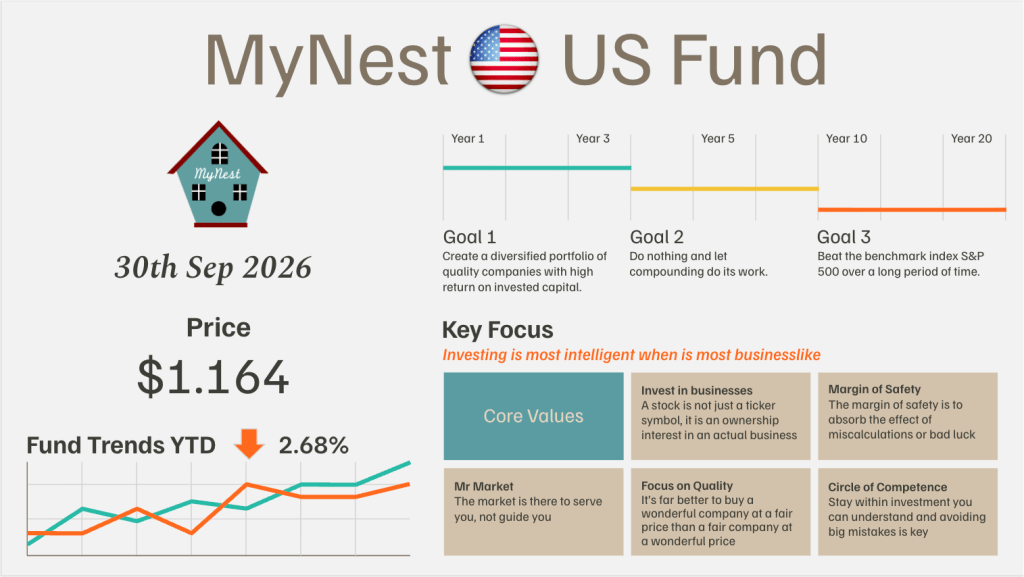
MyNest US Fund Sep 26
The month of Sep brought together two developments that matter to our portfolio: Further progress in the field of AI and a sharp increase in long-term interest rates.
-

The SRS Fund Aug 2026
Aug’s economic update provided another reminder of how closely Singapore has become connected to the global investment in AI and semiconductors.
-
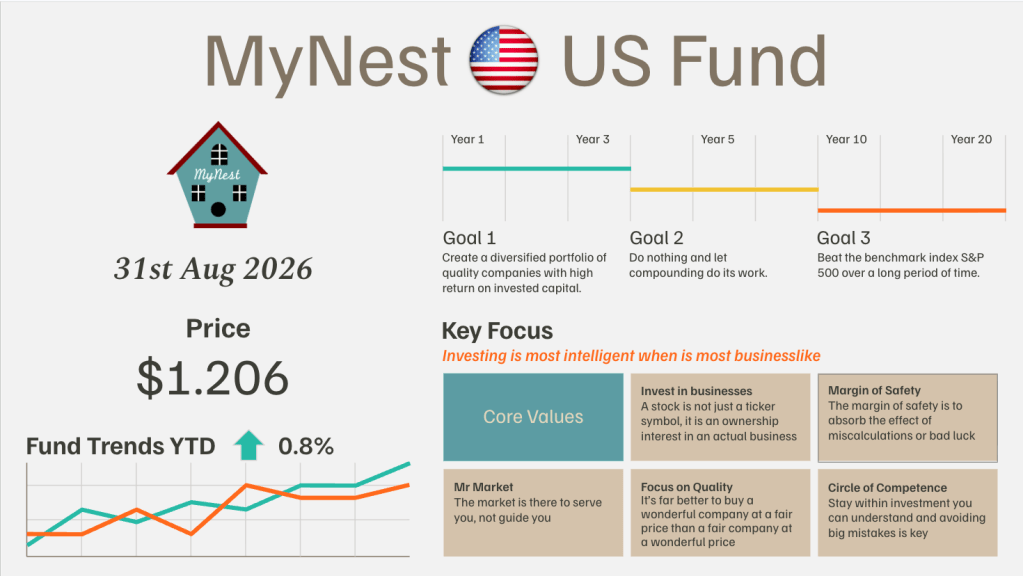
MyNest US Fund Aug 26
The idea behind the “SaaSpocalypse” was simple: if artificial intelligence could write software, generate content and complete business tasks, what would happen to the software companies charging customers to do those things?
-
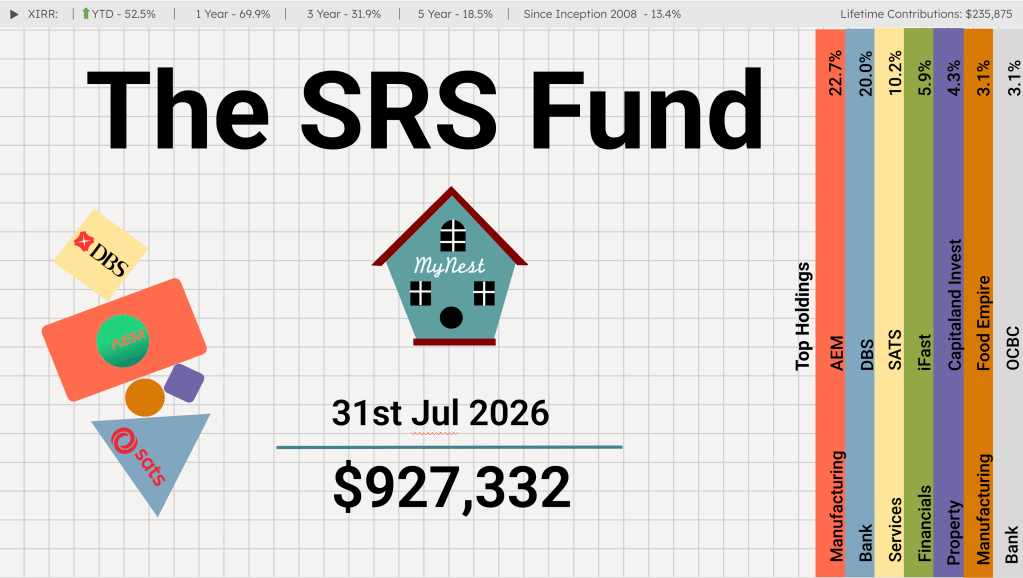
The SRS Fund Jul 2026
For much of 2026, the market’s attention has been firmly fixed on AI, semiconductors and anything connected to the massive build-out in computing infrastructure.
-
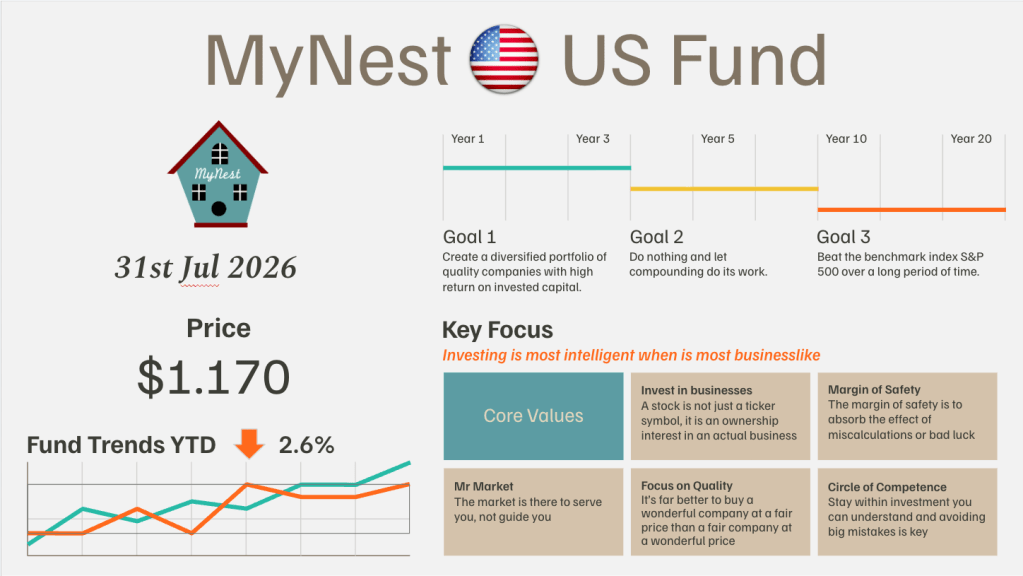
MyNest US Fund Jul 26
After spending a long period watching the artificial intelligence infrastructure build-out from the sidelines, we finally decided to join the party—albeit cautiously.

